Monday, 18 April 2022

Reasons Gated Communities Are Growing In Popularity In Real Estate Market

 April 2022


Gated communities are the latest housing trend and are much in demand amongst homeowners all across the country. Gated communities are now being associated with luxury living at its best. Owing to the rising demand for gated communities various coveted and established property developers are investing in building ultra-modern gated communities that are the current market trend and home buyers' needs of today. Among such popular gated communities is Godrej Meridien Sector 106 Gurgaon which offers myriad amenities to its homeowners. Given below are a few reasons gated communities are getting popular over time.
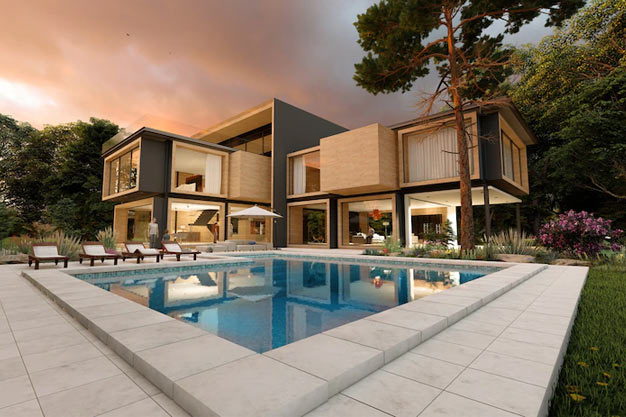


Modern Structure

The great draw to gated communities is their modern structure. The place offers additional security compared to flats, townhouses, etc. The use of modern technology with controlled entry and exit from the main entrance, CCTV camera, etc at every corner of the compound aids in controlling criminal activities within the area. Security is slowly becoming a modern-day rising concern and with the gated community it is easier to feel safe.


Gamut Of Amenities On Offer

Gated communities come with a gamut of amenities on offer swimming pools, gyms, tennis courts, auditorium, WIFI connection, convenience stores etc that are part of the integrated project. The residents can enjoy these amenities without having to travel far. These types of amenities are not always present in other residential buildings or societies. However, one has to note that these amenities are not free of cost for residents. They have to pay a monthly maintenance fee to use all the amenities within the community.


Top Quality Construction

Another advantage of buying residential property in a gated community is that the builders use high-quality construction materials for building structures. gated communities are known to be luxurious properties and hence builders like Taj, Godrej, etc use the premium quality raw material to ensure that the structure has flawless finishing's to attract high-end home buyers. The quality construction ensures that the building will be durable for a long period. Residential Projects in Sector 106 Gurgaon is a new project that provides 3, 2, and 4 BHK apartments and Penthouses to home buyers at competitive rates.


Sense Of Community

A gated community provides community space for residents to celebrate festivals, functions, etc. It allows residents to get together and know each other and become a part of each other life. Today people have busy and hectic work and home schedules and have less energy to go out and make friends but with community living it becomes easier to mingle and make friends. The sense of community is another reason gated communities are rising in popularity today.

Gated communities today are not only luxurious but also promote sustainable living through initiatives like rainwater harvesting, water- treatment plant, the use of energy-efficient lighting, etc. The builders are also working hard to ensure that gated communities come with environmentally friendly measures to make them more appealing to home buyers and also reduce the carbon footprint on the planet

However, when you are looking to buy a residential property in a gated community you must opt for a reputable builder to ensure value for your investment. Gated community residential properties can be expensive therefore make sure that your property has all the high-end finishings and amenities that you are looking for that meet your lifestyle requirement. You can also hire a real estate agent to help you find a gated community in a reputable neighbourhood within your budget. Make sure that you conduct proper research on the preferred residential property in the gated community to make an informed investment decision. You can also compare the prices of penthouses within the gated community of various builders to get the best deal.

TO KNOW MORE ABOUT RESIDENTIAL TOWNSHIP PROJECTS IN THANE VISIT REAL ESTATE THANE CREDAI MCHI THANE UNIT

Sunday, 17 April 2022

CHS's NOC not needed to sell, rent flats, says Maharashtra housing minister Jitendra Awhad

 MUMBAI: A flat owner does not require a no-objection certificate from the housing society to either sell or rent a flat, reminded state housing minister Jitendra Awhad, speaking up against increasing prejudices in society.


"Housing societies will not issue you an NOC if you want to sell your flat to someone from the minority community, a Dalit or from a backward community. There are unwritten rules that flats in a particular society can be sold or rented to only a person who is a vegetarian, Jain or some others. This is illegal. The cooperatives department has clarified that no NOC is required and residents can complain to the deputy registrar," he said.

‘Even banks insist on hsg soc NOC for loans’

State housing minister Jitendra Awhad, who is the NCP MLA from Mumbra, said all that a flat owner needs from a housing society at the time of selling a flat is a no dues pending certificate.

"Over a period of time, this has led to all kinds of conditions being imposed, which divide society," he said. The NCP Mumbra MLA was speaking up against hardening prejudices - the recent ban on sale/consumption of meat during Navratri being a case in point.

In 2014, the state cooperatives department issued housing bye-laws, where it is explicitly stated that no NOC is required for letting out or selling a flat. Bye law no. 38 of the cooperative housing society rules states that for sale and purchase of flat, NOC from the society is not required while bye law no. 43 states that NOC from the society is not required to sub-let the flat. The bye laws also say that if a person needs the NOC, it must be issued within 30 days.

Ramesh Prabhu, chairman, Maharashtra Societies Welfare Association, said as due diligence, it is always advisable to take an NOC from the society to avoid any future hassle. "The NOC is required in case there is some issue such as dues pending, dispute between heirs, or the property has been attached by the income-tax department, etc. Even banks insist on the NOC for housing loans as the society would be aware of these issues," he said.

Prabhu said obtaining an order from the deputy registrar in case a society refuses to give an NOC is a time-consuming process. "If the government is really serious about ending such discrimination and harassment, it must issue a Government Resolution making non-issuance of NOC a cognisable offence," he said.

Increase in stamp duty in Mumbai affecting real estate market

 The Maharashtra Government recently announced to impose Metro cess from April 1 2022. An additional 1 percent cess will be levied on all property purchased from April 1 in Mumbai, Pune and Nagpur. | FPJ Correspondent


The residential segment was the only silver lining in an otherwise tepid 2020 for the real estate sector. While residential sales were adversely affected between April and June 2020 due to the uncertainty resulting from the COVID-19 virus outbreak; they bounced back strongly between October 2020 and March 2021. The market demonstrated a commendable recovery by recording huge sales in Q3 and Q4 of 2020/21.

The Maharashtra Government recently announced to impose Metro cess from April 1 2022. An additional 1 percent cess will be levied on all property purchased from April 1 in Mumbai, Pune and Nagpur. This cess is for funding the Metro rail projects and transport-related projects in the state. The 1 percent Metro cess is expected to augment revenues of the Metro rail services and service the loans, which funded the Metro project. The cess will take the stamp duty on property registration from 5 percent to 6 percent in Mumbai and from 7 percent in Pune, Nagpur and Thane.

Mumbai witnessed 96 percent of pre-COVIDsales in Q4 2021, according to a report by JLL, and sales increased by 30 percent and 130 percent on a year-over-year basis in 2021. Demand momentum appears to be returning, and purchasers in the affordable and mid-segment will feel additional cost burdens during such a time. In the current market recovery, the Metro cess will be detrimental. While we understand that Metro Works need to be properly funded by the State Government to de-clutter the cities and ease traffic, we need to rationalize why the burden of such costs have to be borne solely by Homebuyers.

Further, the timing of this decision should also be brought into question; It has only been 2-3 quarters since residential sales volumes have seen increase. Buyers seem to be shaking off the COVID-19 uncertainty and returning to making purchase decisions. Maharashtra is already one of the most expensive states to own property and increasing transaction costs are bound to affect volumes.

At a global level, we are dealing with a war which has further affected already high input costs for developers. Both Steel and cement prices are trading at all-time highs and other input costs are also on the rise. Keeping this in mind, a reduction in sale volumes and/or sale values could provide very detrimental for the real estate industry.

Therefore, placing the burden of funding metro works on new homebuyers was probably not the best way to raise money for metro construction work. This could have been done in several other ways. One such way would have been to marginally increas property tax. Keeping in mind the number of people that pay property tax, the increase would have to be so miniscule that it wouldn’t have affected the day to day lives of individual or family. With a wide base, the collections would also have potentially been higher. Further, it would also be a more equitable way to treat the matter as the metro, once constructed, will eventually benefit everyone and not only those who purchase homes.

Monday, 11 April 2022

Luxury real estate market to see robust growth in 2022-23. Should you invest?

 April 11, 2022


The coronavirus pandemic had slowed down the investment spree in the real estate market but the reopening of the property markets has led to an increased interest of the uber-rich in the real estate sector. According to a recent survey, the HNIs and the ultra-rich investors are very keen on investing in the property market, especially in the properties segment of over ₹5 crore.

Analysts believe that as the real estate market is resurgent and positive of a robust recovery in the year 2022-23, the luxury real estate market will naturally pick up and aid in the overall real estate recovery cycle.

If the metro cities of Delhi and Mumbai are taken as samples, the year 2021 saw multiple property deals worth over 100 crores.

“The commercial capital of Mumbai is preferred by the ultra-rich. In this case, the short term stamp duty waiver announced in the wake of the Coronavirus crisis played a huge catalyst for the high-end property transactions. The High Net Worth Individuals (HNIs) made use of the occasion and saved a significant amount in stamp duty charges. We believe that the high-value investors who are continuously on the lookout for high-end properties go for only branded and established developers with a proven track record. It makes sense as the investors do not want to run into any trouble due to the procedural flaws from the developers’ side," said Annuj Goel, MD, Goel Ganga Developments.

Nakul Mathur, MD- Avanta India said Delhi has remained the hot favourite of the uber-rich. Multiple deals of up to ₹1000 crore were registered in the capital in the year 2021. Areas such as Lutyens’ zone, Vasant Vihar and South Delhi remained the hot real estate destinations. We believe that trend will remain the same in the upcoming year.

Suren Goel, Partner- RPS Group said one trend that will rule the luxury market is the preference for ready-to-move-in properties. The luxury investors are wary of believing in promises of under-construction properties and want immediate possession.


Saturday, 9 April 2022

Kitchen steel rack designs: 7 ideas for your dream kitchen

April 2022

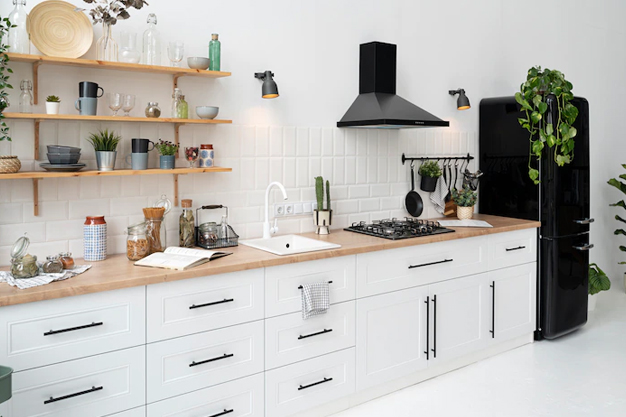
If you are remodelling your kitchen, you should start with the essentials, before taking down or building any walls. Prioritise your storage needs. This is where kitchen steel rack design comes into play. You can keep your kitchen organised with steel racks and shelves.


Best kitchen steel rack designs for an organised kitchen

Here is a list of top kitchen steel rack designs that would transform your kitchen.


1. Basic kitchen steel rack design

Are you looking for a place to store your teapots, mugs and other crockery sets? Consider this stainless kitchen steel rack design with two levels for separating your utensils. Place your teacups and pots on the top half of this stainless steel rack and your plates, spoons and bowls on the lower half. This rack is simple to use and can be placed anywhere in the kitchen.


2. Kitchen steel rack: Space-efficient hangers

You may choose a two or three-tier hanging kitchen rack to keep all spice jars together. This shelf is made of stainless steel, ensuring its longevity and corrosion resistance. As you will be hanging this rack in the kitchen, you can utilise the vertical space to store jars and containers that are normally placed on the kitchen counter.


3. Lift-up Pegasus kitchen steel rack design

If you are seeking a contemporary method to keep your dinnerware, this steel lift-up Pegasus rack may fit your needs. This Pegasus includes a lift-up mechanism with racks for plates and cups. You can now neatly and securely arrange your white ceramics or glass jars on the top rack space and your coffee or tea containers and cups on the bottom rack of this steel kitchen shelf. This Pegasus kitchen steel rack design is ideal for those who want to keep their ceramics out of the reach of children, to avoid breakage and mishaps.


4. Kitchen steel rack design for sink

This kitchen rack may be positioned above or next to a kitchen sink. This type of single-shelf kitchen steel rack design can save space on the kitchen countertop. It is also ideal for the empty space on the wall. These racks are made of stainless steel and come in a variety of colours to complement the decor of your kitchen.


5. Full-length kitchen steel rack design

Are you looking for a rack to keep your belongings or exhibit your plants? Check out the stainless steel kitchen rack shown below, for inspiration. You may use such full-size stainless steel rack shelves to store vegetables and fruits. It can also be used to exhibit crockery and plants or to store spices. These kitchen steel racks are a fantastic method to showcase your valuable China and antique dishes.


6. Kitchen steel rack design: Simple hanging hooks

Install this useful wall storage rack, preferably against a white wall, to hang your kitchen accessories like cutting boards, wooden or steel serving spoons, or spatulas. These storage options are open, have a breezy appearance and are durable and compact. When not in use, keep it dry. Wipe it clean regularly to prevent dirt from accumulating on the rods. Apart from being visually appealing, such hanging racks also offer versatility, because they can be easily adjusted.


7. Kitchen steel rack design for stacking dishes

This kitchen steel rack design is something that every kitchen can use. A dish rack improves ventilation and drainage, which shortens the drying time. Allowing the dishes to dry in the air is also a healthier alternative than towel drying, because you never know how clean or unclean the towel is. However, after finishing, fully dry the rack to avoid rusting. You will be able to maintain your kitchen looking brand new this way.


Rental Properties: Pros and Cons

March 2022

Rental Properties: An Overview

The idea of buying a home or apartment to rent out for profit may sound alluring. But buying a rental property for income and long-term capital appreciation can have its ups and downs. For example, the housing market can fluctuate depending on location, supply and demand, and the economy.

Financially speaking, in order for the rental property to be really profitable, the return you reap should be greater than what you could earn in conservative investments, such as bonds and dividend-paying blue-chip stocks, because of the real risks involved. And on the human side, not everyone has the ability to manage property and tenants.


Pros of Rental Properties

There are several benefits to owning a rental property. They include:


Tax Benefits

The Internal Revenue Service allows you to deduct many expenses connected with rental property in the categories of:

* Ordinary and necessary expenses

* Improvements

* Depreciation


This means that you can deduct your insurance, interest on your mortgage, maintenance costs, and physical wear-and-tear on your property.

Depreciation may produce a nominal loss, which in turn you may deduct against other income. In other words, you may achieve net positive cash flow from the rental income minus expenses and still have a net loss for tax purposes. But be aware that depreciation also reduces the cost basis of a property for calculating capital gains when you sell your property.

In addition, the 2017 Tax Cuts and Jobs Act offers a number of tax benefits for landlords. If you own a flow-through entity (also known as a pass-through business) and operate it as a sole proprietorship, limited liability company, partnership, or S corporation, you now may deduct an amount equal to 20% of your net rental income—as long as your total taxable annual income from all sources after deductions is less than $250,000 for singles or $500,000 for married couples who file jointly.


Seasonal Rentals

If you rent your property seasonally, you may use it yourself for 14 days per year—or 10% of the number of days that you rent to others at a fair market price—and still be able to deduct your expenses.


Renting Extra Space

You can also treat a room or area of your home—such as a garage, basement, or accessory dwelling unit—like a rental, writing off a percentage of the mortgage interest and other expenses against its income, although you should be aware of the potential pitfalls of renting out extra space, including local zoning rules.

Cons of Rental Properties

There are also drawbacks to owning a rental property. They include:


Lack of Liquidity


Real estate is not a liquid asset. Even in the hottest market, it can easily take several months to complete a sale. And if your timing is driven by an emergency or other unexpected event, your need to sell fast might not garner the best price.


Rising Taxes and Insurance Premiums


The interest and principal of your mortgage may be fixed, but there is no guarantee that taxes will not rise faster than you can increase rents. Insurance premiums may also spike, as they have in the wake of natural disasters.


Difficult Tenants


Despite your due diligence in vetting prospective renters, you could wind up with tenants who are not ideal. For example, they could be needy or demanding, pay late, forget to turn off the water, and so on. Or they could be destructive, in which case the depreciation allowance in the tax code may be sorely inadequate. You can, however, always add a rider to the standard lease form that spells out rules about occupancy, pets, smoking, tenant insurance, and the like. A security deposit can also be helpful here.


Neighborhood Decline


In an ideal scenario, your investment property will flourish amid other well-maintained dwellings and local amenities will improve. As a result, your cash flow will increase steadily and your costs remain stable. However, neighborhoods can change and your investment could depreciate over time. You should pay attention to the local politics where you invest, just as you would where you live. With some due diligence, you can minimize this exposure.


Unfavorable Changes to Tax Code


The tax code is not immune to change. It could change in ways that would either reduce or eliminate some or all of the tax benefits for homeownership and flow-through businesses.


Landlord Role


Being a landlord is not for everyone. You may feel shy about increasing rents or be protective of the way others treat your property, which can lead to conflicts. You may even become friends with your tenants or they already may be family or friends. If you cannot be firm about rent increases or property care, for example, you could wind up collecting rent that is well below market price, or with a property that is undervalued.


Upkeep


In maintaining a property, minor and major repairs arise. Some property owners can save money by doing the work themselves. However, most lack the time, tools, or skills for home repair. Expect to shell out periodic contractor fees.


Special Considerations

Whether you are buying a primary home or a rental property, it is important to consider what's happening with mortgage interest rates. Low fixed-rate mortgage debt is generally a good hedge against inflation. If you are a landlord, periodic rent increases are one way of offsetting inflationary rises in property upkeep expenses.

Home loan guide: How to decide the lender and tenure of your home loan?


March 2022

Should you choose a home loan from a bank or a housing finance company? What are the loan tenures and interest rates that you can avail? Housing.com gets answers from experts in a webinar on ‘How to decide lender and tenure of your home loan?’.


For prospective home buyers, opting for a home loan is a significant step in their home-buying journey. With several banks and financial institutions in the market today, selecting the right lender is not an easy decision to take. Often, a borrower may be more inclined to choose a lender offering the lowest interest rate. However, there are other crucial factors that need to be considered to ensure a comfortable loan repayment experience. Emphasising this idea, experts at a webinar conducted by Housing.com on the topic ‘How to decide lender and tenure of your home loan?’ shared valuable insights to help individuals make an informed decision on picking the best lender and home loan tenure.


The panelists at the webinar included Sanjay Garyali (business head – housing finance and emerging market mortgages, Kotak Mahindra Bank) and Rajan Sood (business head – PropTiger.com). The session was moderated by Jhumur Ghosh (editor-in-chief of Housing.com News) and co-branded by Kotak Mahindra Bank.


Where can you get a home loan?

Speaking on the importance of preparation for a home loan, Garyali said, “One of the key parameters one has to look at, is the credibility of a financial institution. A home loan may not be the only product that a customer may seek from a financial institution. One must look at whether the lending institution gives visibility on multiple products as, subsequently, a customer may like to change the tenor and rates, opt for a top-up plan on the existing loan, or go for another loan from the same company. So, one should not look only from the perspective of the home loan interest rate when choosing a home loan.”

Typically, an individual may prefer to get a home loan from a bank where he or she is already a customer. For such regular customers with a good track record, banks may also provide flexible options in terms of rates in the future. It can be a private bank, a public sector bank or any NBFC that an individual may be considering for a home loan. Broadly, one must see whether that company is capable of catering to the multiple needs of a customer in the long run, he added.

Highlighting the fact that the association between a home loan borrower and the lender is a long-term one, Rajan Sood remarked, “Buying a house is one of the biggest decisions of an individual in his or her lifetime. One of the important decisions related to it, is choosing a lender for a home loan. However, the decisions around choosing a lender specifically for a housing loan and for other financial products that one may opt for in the future, cannot be taken separately.” He suggested that home buyers look at the rate of interest offered by different lending institutions, as the foremost thing when seeking a home loan. Another crucial factor that borrowers should see is the loan amount that one is eligible for, as decided by the lending institution. He further added that there are other factors to keep in mind like processing fees, prepayment terms and conditions, the company’s track record, the ease of documentation and the quick turnaround time, before going ahead with a lender.


The shift towards digital experience in the home loan journey

Bringing attention to the digital preparedness of the financial institutions and banks, especially in this current pandemic scenario, Jhumur Ghosh said, “Home loan applicants do not want to go through a lot of paperwork and they want the process to be done in a streamlined manner. Customers today are opting for banks that are digitally prepared, making lives simpler for those opting for home loans.”

Garyali concurred that banks were taking steps to make things convenient for customers. He also highlighted the emerging industry trend of assisted journeys pertaining to home loans and secured lending, where customers look for personalised support and face-to-face interactions with their lenders.

According to Sood, the preference of home buyers towards the digital medium has increased during the past three to four years. “As far as the pre-qualification process for the loan is concerned, most of the customers prefer the online mode. Financial institutions have been focusing on innovation around providing a digital experience for customers. About 50% of the overall home loan process is happening online. If a financial institution can provide an in-principle approval, based on the information provided by customers online, the keenness to close property deals significantly goes up. However, the overall home loan process cannot be completely done digitally and customers prefer the assisted part of the process.” he observed.


What are the buyers’ preferences?

Usually, real estate developers have tie-ups with financial institutions for providing home loan solutions for their customers. Garyali observed that smart home buyers today, who are digitally savvy and have access to information online, prefer to negotiate with the developers on property rates while weighing their options on lenders who provide them with the best home loan options. Agreeing that home buyers view these aspects separately, Sood shared that many home buyers prefer such tie-ups since that reduces their efforts in independently looking for a lending institution.

Ghosh advised that home buyers must keep their options open and decide, after analysing the different scenarios.


Should you go for a shorter loan tenure or longer tenure?

While choosing the right lender is one aspect of the home loan journey borrowers are dealing with, many are also unable to decide the ideal home loan tenure. One must note that opting for a longer loan tenure helps one repay the loan over a longer period, with the EMIs becoming quite affordable. On the other hand, a shorter loan tenure will result in higher EMIs. According to the experts, tenure is a key factor in choosing the loan amount one may be eligible for when taking a home loan. Going for a relatively longer tenure will help one get a higher loan amount for the same salary. The panelists advised that choosing a suitable home loan tenure normally depends on a person’s financial situation and requirements.


Things to remember when opting for a home loan

According to the experts, many home-seekers find applying for a home loan a viable option since it offers various tax benefits. Home loan borrowers are eligible for tax deductions on principal repayment and the interest component and other tax benefits on taking a joint home loan. The experts suggested keeping these points in mind when opting for a home loan.

Sharing more insights on home loan eligibility, Garyali talked about how lending institutions viewed salaried individuals and self-employed individuals differently when assessing their eligibility. He said, “Around 75% of the home loan market comprises customers belonging to the salaried class while the remaining 25% belong to the self-employed category. It is easy to arrive at the eligibility of salaried individuals, as they have a fixed income from salary. On the contrary, for self-employed individuals, the bank or financial institution must get into the nitty-gritty of verifying the various sources of income and several other aspects, thus taking a longer processing time on the part of the lender.”


Fixed rate vs floating rate

As per the experts, certain banks and financial institutions offer a fixed rate for a home loan for a specified period. However, that may mean a premium over the prevailing floating rate, which does not make financial sense for borrowers. On the other hand, the floating rate does not depend on the external environment but varies based on the RBI’s repo rate. In the current regime, experts felt that since the home loans have been linked to the benchmark set by the RBI, it should give customers the confidence to opt for floating interest rates.


Pre-approved loans: Are they beneficial?

A pre-approved loan is where a lender sanctions a loan for a borrower before selecting a property. As per Garyali, pre-approved loans may be merely beneficial for zeroing in on a property and knowing one’s eligibility for a home loan amount. Sood pointed out that pre-approved loans help prospective home buyers since that establishes a sense of confidence and makes them well-acquainted with the entire home loan process.

Responding to how long the low-interest rates may last, Garyali talked about retail inflation and its impact on the home loan interest rates. He said that interest rates may go up and that borrowers would need to assess the situation and decide whether it was the right time for them to go for a home loan. Sood noted that home loans are long-term investments and interest rates may change as they are linked to the RBI’s repo rate. However, he said that any change in home loan interest rates may not significantly impact a prospective home buyer’s decision of purchasing a house.